Death and taxes: How the right analysis for life insurance changes the picture
By Michael J. Rothman and Kristin Williams
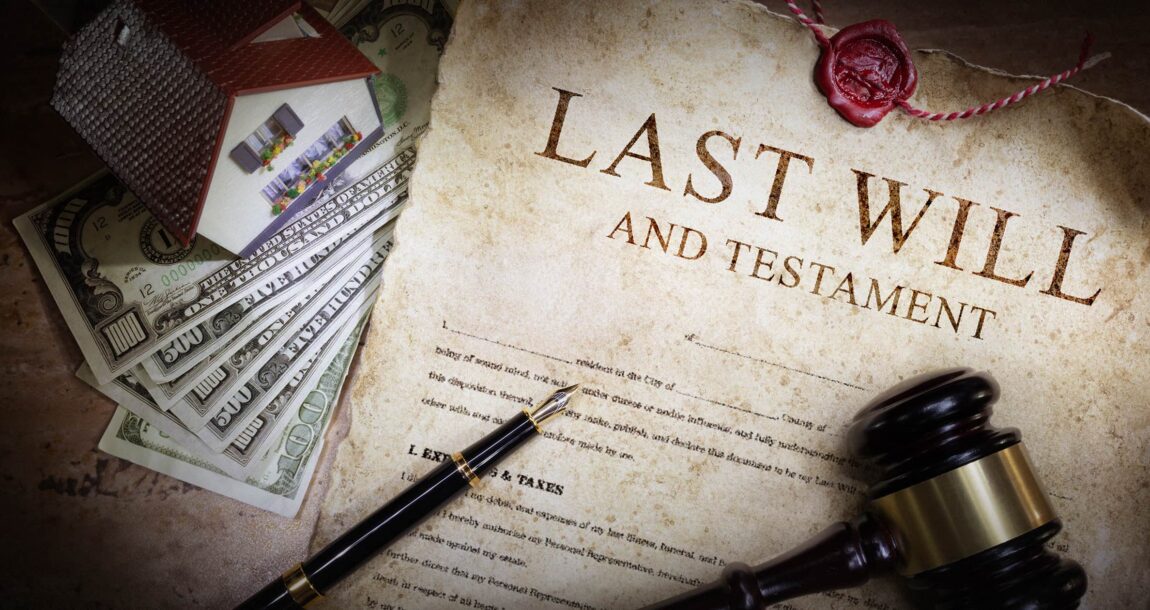
Every substantive analysis of life insurance is based on the same foundational math error: It evaluates a death benefit product as though it were an investment. This makes it easy for advisors to dismiss the importance of life insurance for their high net worth clients. Their clients don’t want to focus on death, so they are happy to agree with an advisor who misinterprets the benefits of life insurance. But what happens when their legacy depends on an influx of tax-efficient liquidity? The most important planning tool for generational wealth is life insurance, and it was overlooked because the advisor used the wrong analysis.
Cash value in Year 5 becomes the measuring stick. Commission as a percentage of premium becomes the indictment. Illustrated returns, compared against an equity benchmark, become the cautionary tale. But for a product designed to deliver a tax-advantaged death benefit at the moment of maximum financial need, those are not the right questions.
This matters because sophisticated clients often make estate planning decisions based on incomplete analysis. In some cases, they dismiss the one tool specifically designed to solve the liquidity problem they must eventually address.
Start with the right question
The correct framework for evaluating any financial product begins with a single question: What need does this product meet?
For life insurance, the answer is simple: to deliver a tax-advantaged death benefit at the intersection of two events whose only uncertainty is when they will occur. Those two events are death and estate taxes. Unlike property/casualty liability or health insurance, life insurance is the only form of insurance that covers a risk that is guaranteed to materialize. Without the liquidity to pay the tax, wealth can be destroyed at the intersection of death and taxes.

For those with liquidity concerns, by using the correct mathematical formula, you will come to one conclusion: Life insurance is arguably the best asset for handling these inevitable generational wealth transfer risks. Focusing the math problem on cash value is analyzing the wrong solution. Shifting the investment analysis from today’s cash value to tomorrow’s death benefit highlights the true power of life insurance.
Consider what a $50 million death benefit represents on a client’s family balance sheet. It is a tax-free, instantly liquid asset that arrives when the estate faces its largest liability. Equities, real estate, private equity and similar alternatives all require liquidation, carry timing risk and can create friction costs at the exact moment the estate is least positioned to absorb them.
The family that has accumulated $80 million in illiquid business interests and real estate does not have a wealth problem masquerading as a liquidity problem. It has a liquidity problem. The return on a life insurance premium is not measured against the S&P 500. It is measured against the cost of a forced asset sale, IRS Code 6166 election with its inherent risks, or an impermissible charitable contribution.
Benjamin Franklin was right about death and taxes
Benjamin Franklin identified two certainties that every person must reckon with: death and taxes. For high net worth families, those events arrive together, creating a liability that is predictable in character and uncertain in timing.
A strategy that excludes the only instrument designed to solve this problem is not rigorous. It includes a gaping hole. Clients deserve to have that gap closed before it’s too late.
For wealth managers, the next portfolio review north of $20 million is worth a second look, not at the investments, but at the liquidity exposures at death. If you don’t model what the estate owes, what is liquid and what must be sold, the review is missing its most consequential question.
For estate planning attorneys, when was the last time you ran a side-by-side model comparing a guaranteed retained annuity trust or discounted family limited partnership against a life insurance policy on the same client fact pattern? If the answer is “never,” the recommendation may be technically correct yet mathematically inaccurate.
For family office advisors, what is the tax and liquidity exposure across multiple generations? Estate tax and liquidity shortfalls are the greatest threats to generational wealth. Planning alone can help, but without life insurance included, the plan will be woefully inadequate.
Life insurance is the only financial instrument designed specifically for the intersection of death and taxes, with tax-free, liquid cash when needed. It does not require predicting market performance, favorable assumptions about interest rates or a liquidity event materializing at the right time.
It simply requires taking the time to do the math and do it right.
© Entire contents copyright 2026 by InsuranceNewsNet.com Inc. All rights reserved. No part of this article may be reprinted without the expressed written consent from InsuranceNewsNet.com.
Michael J. Rothman is chief distribution officer at Succession Capital Alliance. Contact him at michael.rothman@innfeedback.com.
Kristin Williams, JD, LLM, is executive vice president at Succession Capital Alliance. Contact her at kristin.williams@innfeedback.com.
The post Death and taxes: How the right analysis for life insurance changes the picture appeared first on Insurance News | InsuranceNewsNet.